

A valid model must be a no-arbitrage model. That is, one cannot improve on the valuation by specifying different payoffs or by finding different information that predicts payoffs. The Dividend Discount Model (DDM) is a no-arbitrage model, for it is dividends from investing that the investor seeks in order to buy future consumption. Discounting those dividends for the risk they might not be received as measured by the discount rate, r,
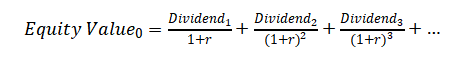
Is a model that forecasts future earnings and book values rather than dividends also a no-arbitrage model?
The answer is: Yes. Here is the outline of the proof. It requires clean-surplus accounting that is introduced in chapter 3:
Book value of equityt = Book value of equityt-1 + Earningst – Dividendst
(Earnings are comprehensive earnings.) So,
Dividendst = Earningst – (Book value of equityt – Book value of equityt-1)
Substitute Dividendst in this expression for Dividendst in the DDM then iterate over periods, you get the residual earnings model:
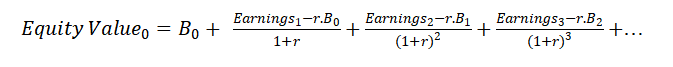
Now there is a remarkable feature about this model: Dividend payout does not affect the value calculated. In M&M terms, the valuation is dividend irrelevant. This gets over the theoretical problem with the DDM. Further, the model exhibits the M&M dividend displacement property. Just as price drops by a dollar for every dollar of dividends paid, so does book value (by accounting principle). You see that in the clean-surplus relation where dividends reduce book value one-for-one. Earnings increase book value, but dividends don’t affect earnings. Accordingly, the residual earnings in the residual earnings model are independent of dividend payout. Very nice!
Here are videos on the residual income model: